Introduction
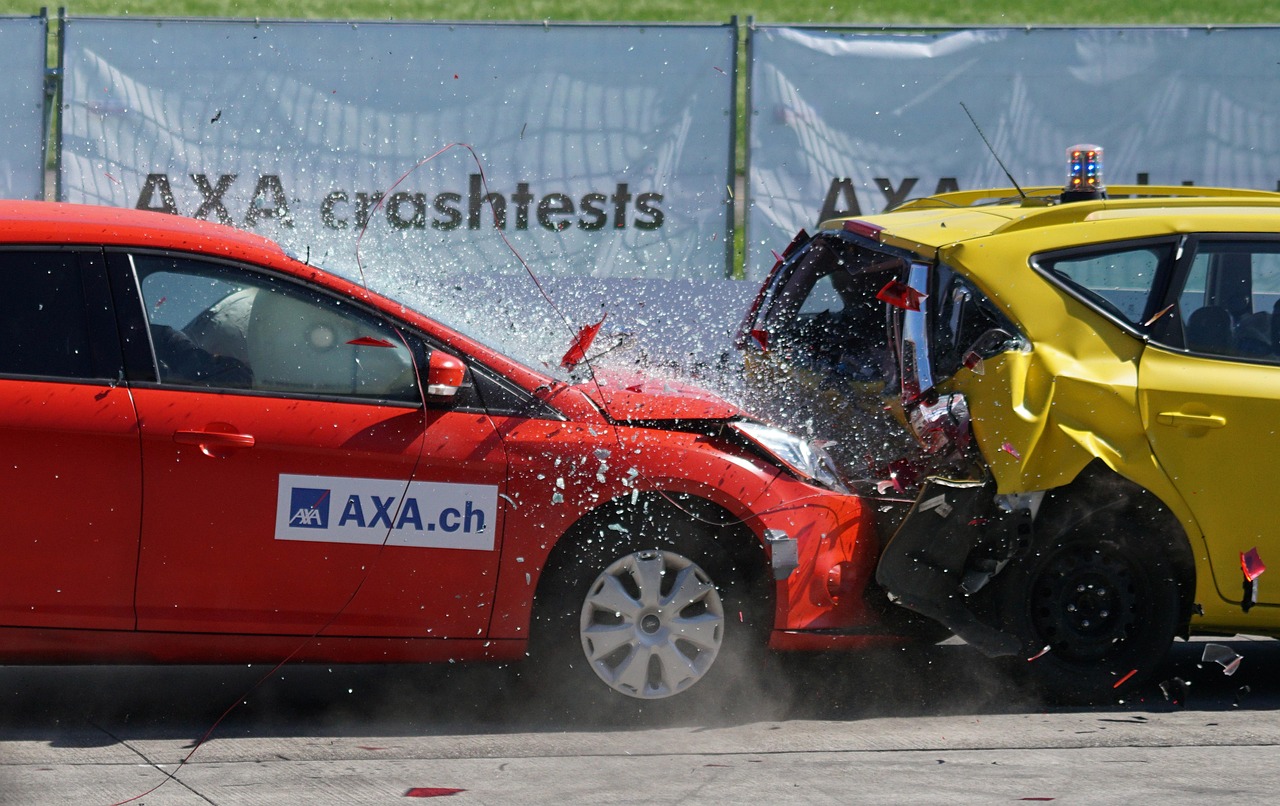
Every driver in 2026 knows that a car is more than just a mode of transport - it's an investment, a safety net, and a legal requirement. Yet, the maze of insurance policies, coverage options, and industry jargon can make it hard to know what you truly need. This article strips away the fluff and focuses on the coverage that protects you, your family, and your wallet in the long run.
Why Car Insurance Matters
In India, the Motor Vehicles Act mandates that every vehicle owner carries a minimum third‑party liability policy. While that satisfies the law, it leaves you vulnerable to significant out‑of‑pocket costs if you're at fault. Beyond the legal minimum, thoughtful coverage helps you manage the financial fallout of accidents, theft, and natural disasters - all of which are becoming more common as climate patterns shift.
Types of Coverage You Should Consider
Below are the core coverages you'll encounter. Knowing what each one does lets you tailor a policy that fits your lifestyle and risk profile.
- Third‑Party Liability - Covers damage to other vehicles, property, and injuries to third parties. Mandatory but limited.
- Comprehensive (Own Damage) - Pays for damage to your own car from accidents, fire, theft, natural disasters, and vandalism.
- Collision - Covers damages to your car resulting from a collision with another vehicle or object, regardless of fault.
- Personal Injury Protection (PIP) - Covers medical expenses for you and passengers, sometimes including lost wages.
- Uninsured/Underinsured Motorist - Protects you if the other driver lacks sufficient insurance.
- Roadside Assistance - Provides towing, battery jump‑start, and lock‑out services.
- Gap Insurance - Covers the difference between your car's market value and the balance on your loan or lease if the vehicle is totaled.
How to Choose the Right Policy
Choosing a policy isn't just about picking the lowest premium. It's a balance between coverage, deductible, and cost.
- Assess Your Vehicle's Value - Newer, high‑tech cars may warrant higher coverage limits. Older cars might be best protected with a lower deductible.
- Know Your Driving Habits - Frequent city driving increases collision risk; long‑haul commuters might value roadside assistance more.
- Set a Realistic Deductible - A higher deductible usually lowers premiums but means you'll pay more upfront when a claim arises.
- Bundle Wisely - Many insurers offer discounts for bundling car insurance with home or renters policies.
- Check the Claim Process - A smooth, digital claim system can save you time and stress during an emergency.
Common Misconceptions About Car Insurance
- "I'm young and safe, so I don't need much coverage." - Young drivers face higher rates, but they also benefit from lower deductibles and bundled discounts.
- "The lowest premium is the best deal." - A cheap policy might lack essential add‑ons, leaving you exposed.
- "Comprehensive and collision are the same." - Comprehensive covers non‑collision events; collision covers accidents.
- "If my vehicle is stolen, the police will handle everything." - Theft claims are processed through the insurer; police reports are just documentation.
Tips to Save Money Without Skipping Coverage
Insurance isn't a one‑time purchase; you can fine‑tune it year after year.
- Maintain a Clean Driving Record - Avoiding tickets and accidents keeps premiums low.
- Install Anti‑Theft Devices - GPS trackers, immobilizers, and alarm systems can earn discounts.
- Use Telemetry‑Based Policies - Some insurers offer usage‑based plans that reward safe, low‑mileage driving.
- Shop Around Quarterly - Even a 5% price drop can save hundreds annually.
- Reevaluate Your Coverage After Major Life Events - A new job, a new home, or a new car can shift your risk profile.
When to Review or Switch Policies
Life changes. So does your insurance need.
- After a Major Accident - A claim can affect future rates; review your policy to avoid unnecessary coverage.
- When You Upgrade or Sell Your Car - A new model may justify higher limits; an older car may not.
- When You Move to a New City - Urban vs. rural risk factors differ, impacting premiums.
- When You Reach a Milestone Age - Some insurers offer senior discounts after 60.
What to Do in an Accident
Quick, organized action can prevent chaos and protect your claim.
- Stay Safe - Move to a safe spot, turn on hazard lights, and check for injuries.
- Call the Police - A police report is essential for most claims.
- Document the Scene - Take photos, note weather, road conditions, and gather contact details of witnesses.
- File a Claim Promptly - Most insurers require claims within 24 - 48 hours for timely processing.
- Use Your Roadside Assistance - If you're stranded, this can get you back on the road quickly.
Questions to Ask Your Agent
When you're ready to buy or renew, ask these to ensure you're not overpaying.
- What is covered under "comprehensive" and "collision" in this policy?
- How does the deductible affect my premium?
- Are there any discounts for bundling or low‑mileage?
- What is the claim payout process and timeline?
- Can I add or remove coverage easily in the future?
Frequently Asked Questions
What is the main point of this article?
It explains the core car insurance coverages you need in 2026, how to choose a policy that fits your lifestyle, and offers practical tips to save money while staying protected.
Who should read this?
Any driver in India looking to understand what insurance actually covers, how to pick the right policy, and how to keep costs manageable.
What is the most important tip here?
Regularly review and adjust your coverage to match your vehicle's value, your driving habits, and life changes.
Where can I learn more?
Check your insurer's website, read official motor insurance guides, and consult independent finance blogs that focus on automotive insurance.
Is this information current?
Yes, it reflects the latest 2026 Indian motor insurance regulations, coverage options, and cost‑saving strategies.